With 12 years of industry experience, including a tenure at a Big 4 firm, Yuk Ming is a seasoned professional specializing in accounting, audit, tax, and project management. A member of both HKICPA and ICAEW, he brings a wealth of expertise to Sleek, particularly in advising and supporting SMEs.
Outside work, Yuk Ming enjoys staying active through tennis and badminton. He also likes watching movies and playing video games in his free time.
97% customer satisfaction from 16,000+ survey responses.
In this article
Share this post
Facebook
LinkedIn
WhatsApp
Copy to clipboard
Key takeaways
HKFRS for Private Entities (HKFRS for PE) is HKICPA’s simplified financial reporting standard for entities without public accountability. It is equivalent to the IFRS for SMEs Accounting Standard.
Eligibility is based on public accountability, not company size. A large private group may qualify, while a small company with publicly traded debt or equity may not.
HKFRS for PE is optional. An eligible entity can still choose full HKFRS, and adopting HKFRS for PE does not require shareholder approval.
A revised standard applies from 1 January 2027. HKICPA issued the revised version in April 2025, with early application permitted.
Using HKFRS for PE does not remove the statutory audit requirement. The reporting framework determines how financial statements are prepared; audit requirements are a separate issue.
Not sure whether PE, full HKFRS or SME-FRS is the one your auditor expects?
What is HKFRS for PE? A simplified HKICPA reporting standard for entities without public accountability. It is equivalent to the IFRS for SMEs Accounting Standard.
Who can use it? Entities with no public accountability that publish general purpose financial statements for external users.
Who cannot use it? Entities with publicly traded debt or equity, or entities that hold assets in a fiduciary capacity for a broad group of outsiders as one of their primary businesses.
When does the revised standard apply? Annual periods beginning on or after 1 January 2027. Early application is permitted.
Your auditor may have told you that your accounts will be prepared under HKFRS for Private Entities, only for you to discover that most online explanations either focus on company formation or reproduce the accounting standard section by section.
The useful starting point is simpler: HKFRS for PE is a simplified reporting framework for entities without public accountability. Eligibility depends on a two-part public-accountability test, not on revenue, headcount, or total assets.
A revised version also applies to annual periods beginning on or after 1 January 2027, so the change may affect your next reporting cycle.
In this guide, you’ll learn:
What HKFRS for Private Entities is and what it’s equivalent to internationally
How the public-accountability test works
Why company size doesn’t determine eligibility
How HKFRS for PE differs from full HKFRS and SME-FRF/SME-FRS
Whether adopting HKFRS for PE affects your audit
What changes under the revised standard from 2027
What is HKFRS for Private Entities?
HKFRS for Private Entities (HKFRS for PE) is HKICPA’s financial reporting standard for entities that don’t have public accountability. It’s designed to reduce the reporting burden for eligible entities compared with full HKFRS.
HKFRS for PE is also Hong Kong’s equivalent of the IFRS for SMEs Accounting Standard issued by the International Accounting Standards Board (IASB). The current Hong Kong version corresponds to the 2015 edition of IFRS for SMEs, while the revised version corresponds to the third edition.
An entity must meet two conditions:
It doesn’t have public accountability; and
It publishes general purpose financial statements for external users, such as non-managing owners, creditors, and credit-rating agencies.
HKFRS for PE is a financial reporting framework, not a tax-return format or a simplified bookkeeping method.
Tip
If a statute or your articles demand a true and fair view, paragraph 3.2 of the standard covers you. Applying HKFRS for Private Entities, with additional disclosure where necessary, is presumed to achieve one. You do not need to bolt on full HKFRS just to satisfy that wording.
Who can use HKFRS for Private Entities?
An entity can use HKFRS for PE if it has no public accountability and publishes general purpose financial statements for external users. Public accountability is determined by a two-part test. Failing either limb means the entity can’t use the framework.
Public-accountability test
What it means
Examples
Public market
Debt or equity is traded in a public market, or the entity is in the process of issuing such instruments for public trading
Domestic or foreign stock exchanges and OTC markets
Fiduciary capacity
The entity holds assets in a fiduciary capacity for a broad group of outsiders as one of its primary businesses
HKFRS for Private Entities is not a size test. Either limb of public accountability closes it: a public market in your instruments, or holding assets for outsiders as a primary business.
The “as one of its primary businesses” qualification is important. Simply holding money or assets belonging to someone else doesn’t automatically create public accountability if that activity is incidental to the entity’s main business.
The standard gives examples including travel and real estate agents, schools, charitable organisations, certain co-operatives, and businesses that receive payment before delivering goods or services.
Does company size determine eligibility?
No. Company size isn’t the eligibility test. A large family-owned group with no publicly traded instruments may qualify, while a small company with publicly traded debt can’t.
Likewise, being classified as a “private company” under the Companies Ordinance doesn’t by itself determine whether HKFRS for PE is available.
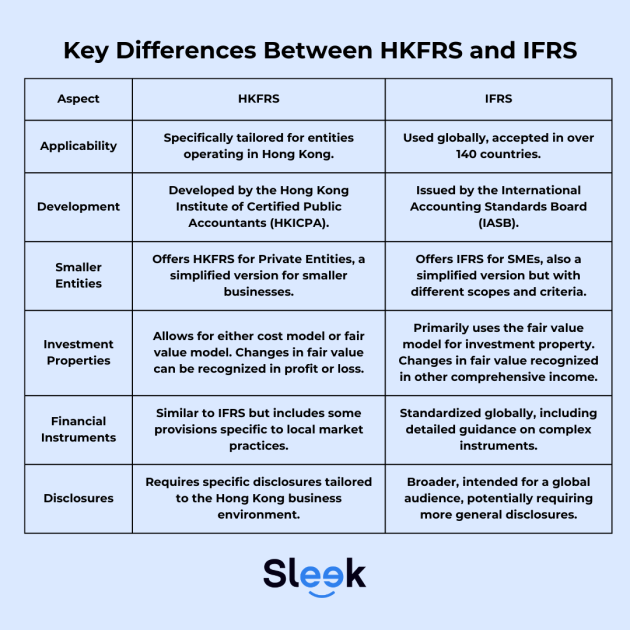
HKFRS for PE simplifies recognition, measurement, and disclosure compared with full HKFRS. The result is a lighter reporting framework for eligible private entities.
An entity that qualifies for HKFRS for PE can still choose full HKFRS. Reasons for doing so may include:
Group reporting: the parent reports under full HKFRS or IFRS and wants a consistent accounting framework
Investor requirements: financing documents or shareholder arrangements require full HKFRS
Bank covenants: a lending agreement specifies the reporting framework
Future listing plans: moving to another framework later may be less efficient if public-accountability requirements are approaching
Your articles, shareholder agreements, financing arrangements, or other contractual documents may also specify the framework to be used. Those requirements should be checked before changing your accounting basis.
How does HKFRS for PE differ from SME-FRF and SME-FRS?
HKFRS for PE and Hong Kong’s SME-FRF/SME-FRS are different frameworks with different eligibility tests. HKFRS for PE is based on public accountability, while SME-FRF/SME-FRS eligibility is linked to the Companies Ordinance reporting exemption and its associated requirements.
An entity may therefore be:
Eligible for both frameworks
Eligible for HKFRS for PE but not SME-FRF/SME-FRS
Eligible for neither and therefore required to use full HKFRS
The distinction also matters for 2027: the revised HKFRS for PE doesn’t automatically change the reporting framework for companies using SME-FRS.
Want year-end accounts kept on the framework you actually chose?
Is HKFRS for Private Entities mandatory, and do you still need an audit?
No. HKFRS for PE is optional for eligible entities, and adopting it doesn’t remove the statutory audit requirement.
An eligible entity can choose full HKFRS instead, and HKFRS for PE doesn’t require shareholder approval before adoption.
The distinction is straightforward:
Reporting framework: determines how the financial statements are prepared
Audit requirement: determines whether those financial statements must be audited
The two questions should be considered separately. Whether a company qualifies for any audit exemption is a different issue governed by the relevant Companies Ordinance requirements.
Important note
Choosing HKFRS for Private Entities does not cancel your statutory audit. A reporting framework decides how the financial statements are prepared. It has nothing to do with whether an auditor has to report on them. Hong Kong companies generally need audited financial statements regardless of which framework produced them.
What changes in the revised HKFRS for Private Entities from 2027?
HKICPA issued a revised version in April 2025, and it applies to annual periods beginning on or after 1 January 2027. Early application is permitted. The revised Hong Kong standard corresponds to the third edition of the IFRS for SMEs Accounting Standard, published by the IASB in February 2025.
The transition is retrospective for the new and amended requirements, with some relief available for entities applying certain amendments.
What are the main changes?
Area
What changes
Revenue — Section 23
Revised to introduce a five-step model; some entities may account for customer transactions differently
Financial instruments — Section 11
New disclosures, including ageing analysis for financial assets and maturity analysis for financial liabilities
Leases — Section 20
Not revised to align with HKFRS 16 in this update
Impairment
The incurred-loss model is retained for financial assets measured at amortised cost
For many companies, the practical planning issue is the revised revenue model. Businesses with multiple performance obligations, variable consideration, or more complex customer contracts should discuss the transition with their auditor before the relevant reporting period.
The effective date is tied to the beginning of the annual period, not the financial year-end itself.
What mistakes do first-time HKFRS for PE users make?
Several recurring misconceptions can make the framework harder to understand than it needs to be.
Treating HKFRS for PE as full HKFRS with sections removed
It’s a self-contained reporting standard, rather than a version of full HKFRS with selected requirements deleted.
Using SME-FRF size thresholds to test HKFRS for PE eligibility
Revenue, assets, and headcount are relevant to the Companies Ordinance reporting exemption and the SME framework, but they don’t determine public accountability under HKFRS for PE.
Assuming HKFRS for PE means no audit
The reporting framework and audit requirement are separate issues. Preparing financial statements under a simpler framework doesn’t, by itself, create an audit exemption.
Waiting until 2027 to consider the revised standard
For periods beginning on or after 1 January 2027, the revised requirements apply. The transition is retrospective, so companies affected by the revenue changes may need to plan before year-end.
Confusing HKFRS for PE with HKFRS 19
HKFRS 19 is a different standard that provides reduced disclosures for eligible subsidiaries that continue to use full HKFRS. HKFRS for PE has a different eligibility test and serves a different purpose.
Assuming HKFRS for PE covers sustainability reporting
Sleek can maintain accounting records and coordinate audit work, but it doesn’t replace the professional judgement or formal opinion of an auditor.
Another provider or a specialist adviser may be more appropriate if you:
Need a formal opinion on a specific accounting treatment
Are undertaking a full framework conversion across a multi-entity group
Need a firm to sign the statutory audit report
Have public accountability and therefore can’t use HKFRS for PE
Need advice on HKFRS S1 or S2 sustainability disclosures
When might Sleek be a suitable fit?
Sleek may be suitable once the reporting framework has been decided and the main requirement is maintaining records and preparing for year-end reporting under that framework.
This may include companies that:
Have an auditor who has already specified the reporting framework and need accounting and tax services aligned with it
Want a year-end financial reporting pack their auditor can work from
Are deciding between HKFRS for PE and full HKFRS and want to understand the practical workload
Have a reporting period beginning in 2027 and want to prepare for the revised revenue and disclosure requirements
Want bookkeeping and audit coordination through one provider
How Sleek helps you report under the right framework
The reporting framework determines how the financial statements should be prepared; the day-to-day accounting records still need to support that framework.
With Sleek, you can:
Keep records on the chosen framework:bookkeeping maintained so the year-end statements fall out of the ledger rather than being reconstructed.
Get an audit-ready year-end pack: schedules, reconciliations and supporting documents assembled the way an auditor expects them.
Coordinate the audit: a single point of contact managing auditor queries instead of routing them through you.
Plan for the 2027 period: the revenue and financial-instrument disclosure changes raised before your year end, not after it.
Sleek doesn’t replace the auditor’s judgement on specific accounting treatments. Questions about whether a particular transaction or contract meets the revised requirements should be discussed with the auditor.
The standard is the Institute’s. The books still have to match it.
Tell us your year end, your framework and who signs your audit. We’ll say what needs to change before the next period starts.
If my facility agreement names HKFRS, can I still use PE?
Yes. The Institute’s test is still public accountability, so a loan clause does not ban PE. The agreement can still require full HKFRS as a contractual reporting obligation even when PE is available, which is why covenants sit in the “you might still choose full HKFRS” list. Read the facility wording before you adopt PE.
Can I switch from HKFRS for PE back to full HKFRS in a later year?
Yes. The standard is an option if you qualify, not a one-way Companies Ordinance election. Moving later is an accounting-policy change for you and your auditor, with disclosure and comparatives to agree in advance. Any framework clause in your articles or a shareholders’ agreement still binds you, the same way it can block the first switch.
If my parent uses full HKFRS, can the Hong Kong subsidiary still use PE?
Yes, on the standard’s own terms. Paragraph 1.6 says a subsidiary whose parent uses full HKFRS or IFRS, or that is part of a consolidated group using them, isn’t prohibited from using HKFRS for Private Entities in its own financial statements, provided the subsidiary itself has no public accountability. Whether the group wants two policy sets is a separate and usually decisive question.
Can I early-apply the 2027 standard in a 2026 year end?
Early application is permitted, so in principle yes. Watch the wording of the effective date, though: it bites for annual periods beginning on or after 1 January 2027, not periods ending then. Early application means voluntarily adopting the revised standard for a period starting before that date, and the retrospective transition requirements come with it. Confirm the mechanics with your auditor first.
Does switching to HKFRS for Private Entities change my Profits Tax computation?
Not directly. Your computation starts from the accounting profit and then applies the Inland Revenue Ordinance, so the framework can move the starting figure while the tax adjustments are made on their own terms. Switching framework isn’t a tax planning move, and where a change in accounting policy shifts recognition timing, the tax treatment needs looking at separately.
View more
Where do I read the actual standard text?
In HKICPA’s Members’ Handbook. The Institute’s HKFRS for Private Entities Information Centre is the entry point, and it separates the currently effective version from the revised version issued but not yet effective. The Institute’s older question-and-answer material is useful for eligibility scenarios, but it carries a 2010 revision stamp, so don’t read it for anything about 2027.