Chester Cheung is the Content Marketing Specialist for the Hong Kong market at Sleek, crafting localized, high-conversion bilingual content that empowers entrepreneurs to make confident business decisions.
Drawing on a background in finance and digital marketing, including roles at HSBC and in the digital agency space, Chester combines commercial rigor and performance-driven storytelling to every piece he ships. His focus is on translating complex business and compliance concepts into clear, actionable insights for busy founders.
Having worked across both structured corporate environments and agile teams, Chester knows what business owners value most: reliable information without the jargon. At Sleek, he leverages this perspective to produce insightful, accessible content that drives customer acquisition and fosters long-term value.
When he’s not writing, Chester is an active runner and an amateur photographer.
97% customer satisfaction from 16,000+ survey responses.
In this article
Share this post
Facebook
LinkedIn
WhatsApp
Copy to clipboard
Key takeaways
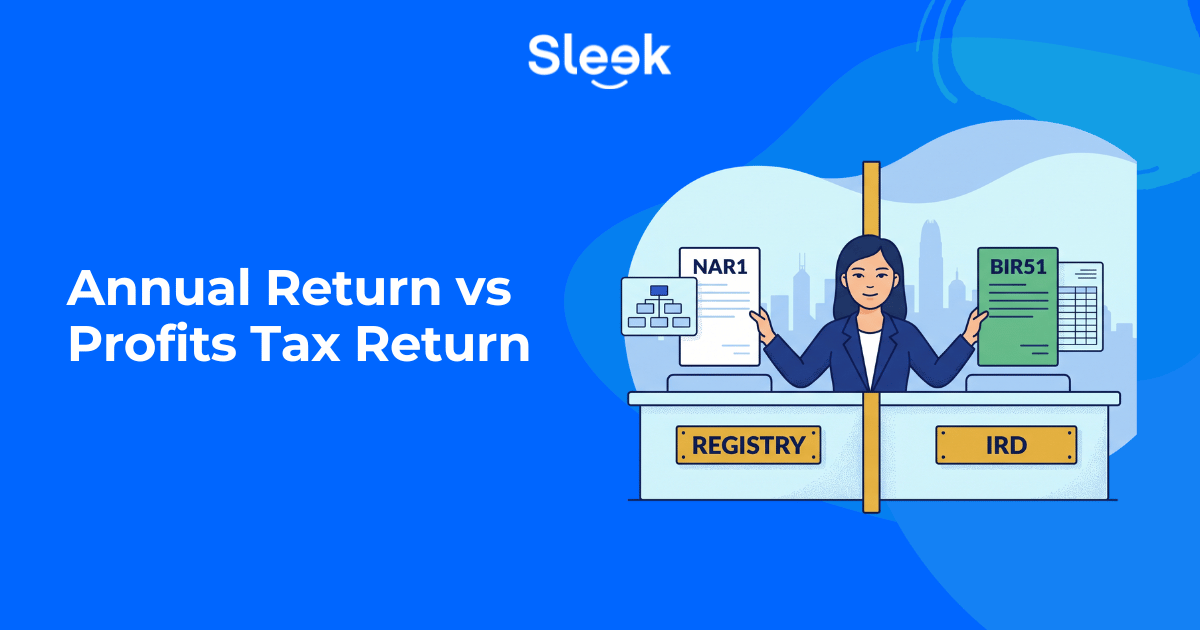
These are not one filing with two names. The annual return goes to the Companies Registry; the Profits Tax Return goes to the Inland Revenue Department.
They ask for different things. A private company’s annual return (NAR1) is a particulars snapshot with no financial figures. A Profits Tax Return (BIR51) needs accounts and a tax computation.
Two clocks, not one. NAR1 runs from your incorporation anniversary. The Profits Tax Return runs from the date the IRD issues it.
Filing one does nothing for the other. The two departments don’t pass your paperwork between them.
Going quiet doesn’t pause either filing. Formal dormancy does, and being inactive is not the same thing.
Annual return (NAR1): filed with the Companies Registry within 42 days after your incorporation anniversary, fee HK$105 on time, no accounts for a private company.
Profits Tax Return (BIR51): filed with the IRD, usually within one month of the issue date. No filing fee, but tax may be payable, and accounts plus a computation are normally required.
Do both: neither discharges the other, and the penalties are separate.
First year: NAR1 arrives on your first anniversary; your first Profits Tax Return usually turns up much later.
Annual return vs Profits Tax Return filings both use the word “return”, but they serve completely different purposes. The annual return (NAR1) goes to the Companies Registry, while the Profits Tax Return (BIR51) goes to the Inland Revenue Department (IRD). They have different information requirements, deadlines, and penalties.
For a private company, the annual return is mainly a corporate information filing. The Profits Tax Return is a tax filing that normally requires financial statements and a tax computation. Filing one doesn’t satisfy the other.
In this guide, you’ll learn:
Which department receives each filing
What the annual return and Profits Tax Return contain
Why their deadlines don’t line up
What happens if you file late
How formal dormancy affects the two obligations
Are an annual return and a Profits Tax Return the same thing?
No. They’re separate filings under different laws, submitted to different government departments. The annual return records the company’s corporate particulars; the Profits Tax Return reports its tax position.
An annual return goes to the Companies Registry and reports who runs and owns the company. A Profits Tax Return goes to the Inland Revenue Department and reports what it earned. Two filings, two deadlines, two sets of consequences.
Here’s the whole comparison in one place, for a private company limited by shares:
Annual return (NAR1)
Profits Tax Return (BIR51)
Filed with
Companies Registry
Inland Revenue Department
Governed by
Companies Ordinance (Cap. 622), section 662
Inland Revenue Ordinance
What it reports
Officers, members, registered office, share capital
Assessable profits
Deadline
Within 42 days after the incorporation anniversary
Usually one month from the IRD issue date
Government fee
HK$105 on time
No filing fee, though tax may be payable
Accounts attached?
No, for a private company
Yes, normally audited accounts plus a computation
If you’re late
Higher registration fees from HK$870 to HK$3,480, plus prosecution and strike-off risk
Fine up to HK$10,000, up to three times the tax undercharged, estimated assessment
There are two important qualifications:
Public companies follow a different annual-return timetable and file certified financial statements.
Guarantee companies have their own return date. The “no accounts” point above applies to private companies, not every company type.
Want NAR1 filed on the anniversary clock, not the tax calendar?
The audit therefore relates to the tax filing, not the annual return.
Which Profits Tax form does a company use?
For corporations, the relevant return is BIR51. Other forms apply to different taxpayer types, including partnerships and non-resident businesses.
When is each one due?
The annual return follows your company’s incorporation anniversary. The Profits Tax Return follows the IRD’s issue date. Because they run on different schedules, you need to track both separately.
Annual return (NAR1)
Profits Tax Return
Clock starts
Anniversary of your incorporation date
The IRD’s issue date on the return
You get
42 days after that anniversary
Generally one month from the issue date
Predictable?
Yes. The date never moves
No. You wait for the letter
Linked to your year end?
No
Yes, if a block extension applies
Annual Return deadline
For a private company, the annual return is due within 42 days after the anniversary of the date of incorporation. The date doesn’t change with your financial year-end and isn’t linked to the IRD’s tax-return cycle.
The Profits Tax Return follows the issue date shown on the return from the IRD. GovHK says it should generally be filed within one month of the issue date. The IRD’s bulk issue generally takes place on the first working day of April.
If you have a tax representative, you may qualify for the block extension scheme, with the actual deadline depending on your year-end code. See the Profits Tax filing deadline guide for the relevant dates.
What happens in the first year?
The two deadlines can be far apart.
Your first NAR1 is due 42 days after your first incorporation anniversary, while your first Profits Tax Return generally arrives much later. GovHK says a newly registered business will generally receive its first return around 18 months after it starts trading or is incorporated, so always check the deadline printed on the return itself.
That means a new company may need to file its annual return well before its first Profits Tax Return arrives. Not receiving a tax return yet doesn’t mean there are no corporate filing obligations.
Tip
Your annual return runs from your incorporation anniversary, not from your financial year end and not from the IRD's April bulk issue. Incorporate in September and NAR1 is an autumn job every year, whatever your accounting date. Filing it "at tax time" is how companies discover the late fee.
What does each filing cost, and what happens if you file late?
The annual return and Profits Tax Return have different costs, deadlines, and penalties. For a private company, the annual return costs HK$105 when filed on time, while the Profits Tax Return has no filing fee but can attract penalties for late filing.
Annual Return fees for a private company
The Companies Registry charges a higher registration fee when an annual return is filed late:
How late?
Rregistration fee
Filed on time
HK$105
More than 42 days but within 3 months
HK$870
More than 3 months but within 6 months
HK$1,740
More than 6 months but within 9 months
HK$2,610
More than 9 months
HK$3,480
The Companies Registry states that the Registrar doesn’t have the power to waive these higher fees. Late filing can also expose the company and its officers to prosecution and can contribute to strike-off action.
Profits Tax Return penalties
There’s no fee to file a Profits Tax Return, but late filing can result in penalties.
The IRD’s stated maximum includes a HK$10,000 fine under section 80(2) of the Inland Revenue Ordinance, as well as a further penalty of up to three times the tax undercharged. The IRD may also issue an estimated assessment based on its own figures.
That’s why the two filings should be treated separately: the annual return has a late-fee ladder, while the Profits Tax Return has a penalty regime.
If you file one, have you filed the other?
No. The Companies Registry and IRD filings are independent. Filing a BIR51 doesn’t prevent annual-return fees or other Companies Registry consequences, and filing NAR1 doesn’t satisfy a Profits Tax Return.
This is an easy mistake to make when an accountant handles the tax filing and the company secretary handles corporate filings.
For example:
Your accountant files BIR51 on time.
Your annual return is still outstanding with the Companies Registry.
Or your company secretary files NAR1 on time while a Profits Tax Return issued by the IRD remains outstanding.
The safest approach is to treat them as two separate compliance deadlines.
Important note
The Companies Registry and the IRD have no "we received the other form" feed between them. A filed BIR51 does not stop annual return late fees accruing, and it does not protect you from strike-off action. Each department only knows about the filing it received.
Does a dormant or inactive company still file both?
Being inactive changes nothing. Being formally dormant changes the annual return. The two words aren’t interchangeable.
Stopped trading (inactive)
Formally dormant
What it takes
Nothing. You simply stop trading
A special resolution delivered to the Registrar under section 5
Annual return
Still due every year, with the fees and the late ladder
Not required (section 663)
Profits Tax Return
File it if the IRD issues one
File it if the IRD issues one
Audited accounts
Required
Exempt (section 447)
If your company has simply stopped trading, it remains an ordinary company in every respect that matters to the Registry.
Watch the timing on the year you declare. The Registry’s dormant companies FAQ says the annual return is still due for that year if the effective date of dormancy falls after the 42nd day after your incorporation anniversary. Declare late in your compliance year and you still owe that year’s filing.
Tax doesn’t switch off the same way. If the IRD issues a Profits Tax Return, you file it. You can file it without audited accounts, though: a company that has delivered a section 5 resolution is exempt from preparing them under section 447, and the IRD accepts dormant companies’ returns on that basis. The steps are on the dormant company page.
What mistakes do companies make when dealing with the two returns?
Treating the annual return as a tax return
They’re completely different filings. NAR1 concerns company particulars and doesn’t include a profit figure or accounts.
Waiting until tax season to file the annual return
The annual return follows the incorporation anniversary, not the tax calendar. Waiting for April can therefore leave the company late without realising it.
Assuming no profit means there’s no Profits Tax Return
If the IRD has issued a return, it still needs to be addressed. A company reporting no taxable profit doesn’t automatically have no filing obligation.
Assuming that stopping trading stops the annual return
It doesn’t. Unless the company has formally entered dormancy under the relevant Companies Ordinance process, the ordinary annual-return requirement continues.
Using the wrong Profits Tax form
BIR51 is the corporation return. Other forms apply to other taxpayer categories, so the correct form depends on the entity and taxpayer status.
When might Sleek not be the right fit?
Some situations go beyond routine filing support. Another adviser may be more appropriate if you:
Are disputing an estimated assessment or a complex penalty matter
Need advice or drafting around a formal dormancy resolution
Need specialist advice on two-tier profits tax rates, offshore claims, or transfer pricing
Need legal or tax advice on a disputed filing position
When might Sleek be a suitable fit?
Sleek may be suitable when you need help keeping the two separate compliance calendars organised.
This may include situations where:
You’ve received a government letter and aren’t sure which filing it relates to
You want the annual return and Profits Tax Return tracked together
Your accounts need to be prepared for audit and tax filing
You’re already late and need to understand the relevant fee or penalty position
How Sleek helps with both clocks
The annual return and Profits Tax Return are separate obligations, but their administration can be coordinated.
Depending on the service scope, Sleek can support areas such as:
No. The annual return is a Companies Ordinance filing for registered companies. A sole proprietor instead deals with business registration and the relevant Profits Tax filing for an unincorporated business.
If we change our financial year end, does the annual return date move?
No. The annual return is based on the company’s incorporation anniversary, so changing the accounting year-end doesn’t change that date. Tax filing dates can be affected because they follow the company’s accounting period and applicable extension arrangements.
Is Business Registration Certificate renewal the same as an annual return?
No. They’re separate obligations. Business registration is an IRD matter with its own renewal cycle, while the annual return is filed with the Companies Registry.
Our company is public. Does the annual return really have no accounts?
No. The no-accounts point applies to private companies. Public companies have a different annual-return timetable and file certified copies of their financial statements, directors’ report, and auditor’s report.
We already filed BIR51. Can the Companies Registry still take action over a missing annual return?
Yes. The Companies Registry’s records and the IRD’s tax-filing records are separate. Filing the Profits Tax Return doesn’t resolve an outstanding annual return.