With 12 years of industry experience, including a tenure at a Big 4 firm, Yuk Ming is a seasoned professional specializing in accounting, audit, tax, and project management. A member of both HKICPA and ICAEW, he brings a wealth of expertise to Sleek, particularly in advising and supporting SMEs.
Outside work, Yuk Ming enjoys staying active through tennis and badminton. He also likes watching movies and playing video games in his free time.
97% customer satisfaction from 16,000+ survey responses.
In this article
Share this post
Facebook
LinkedIn
WhatsApp
Copy to clipboard
Key takeaways
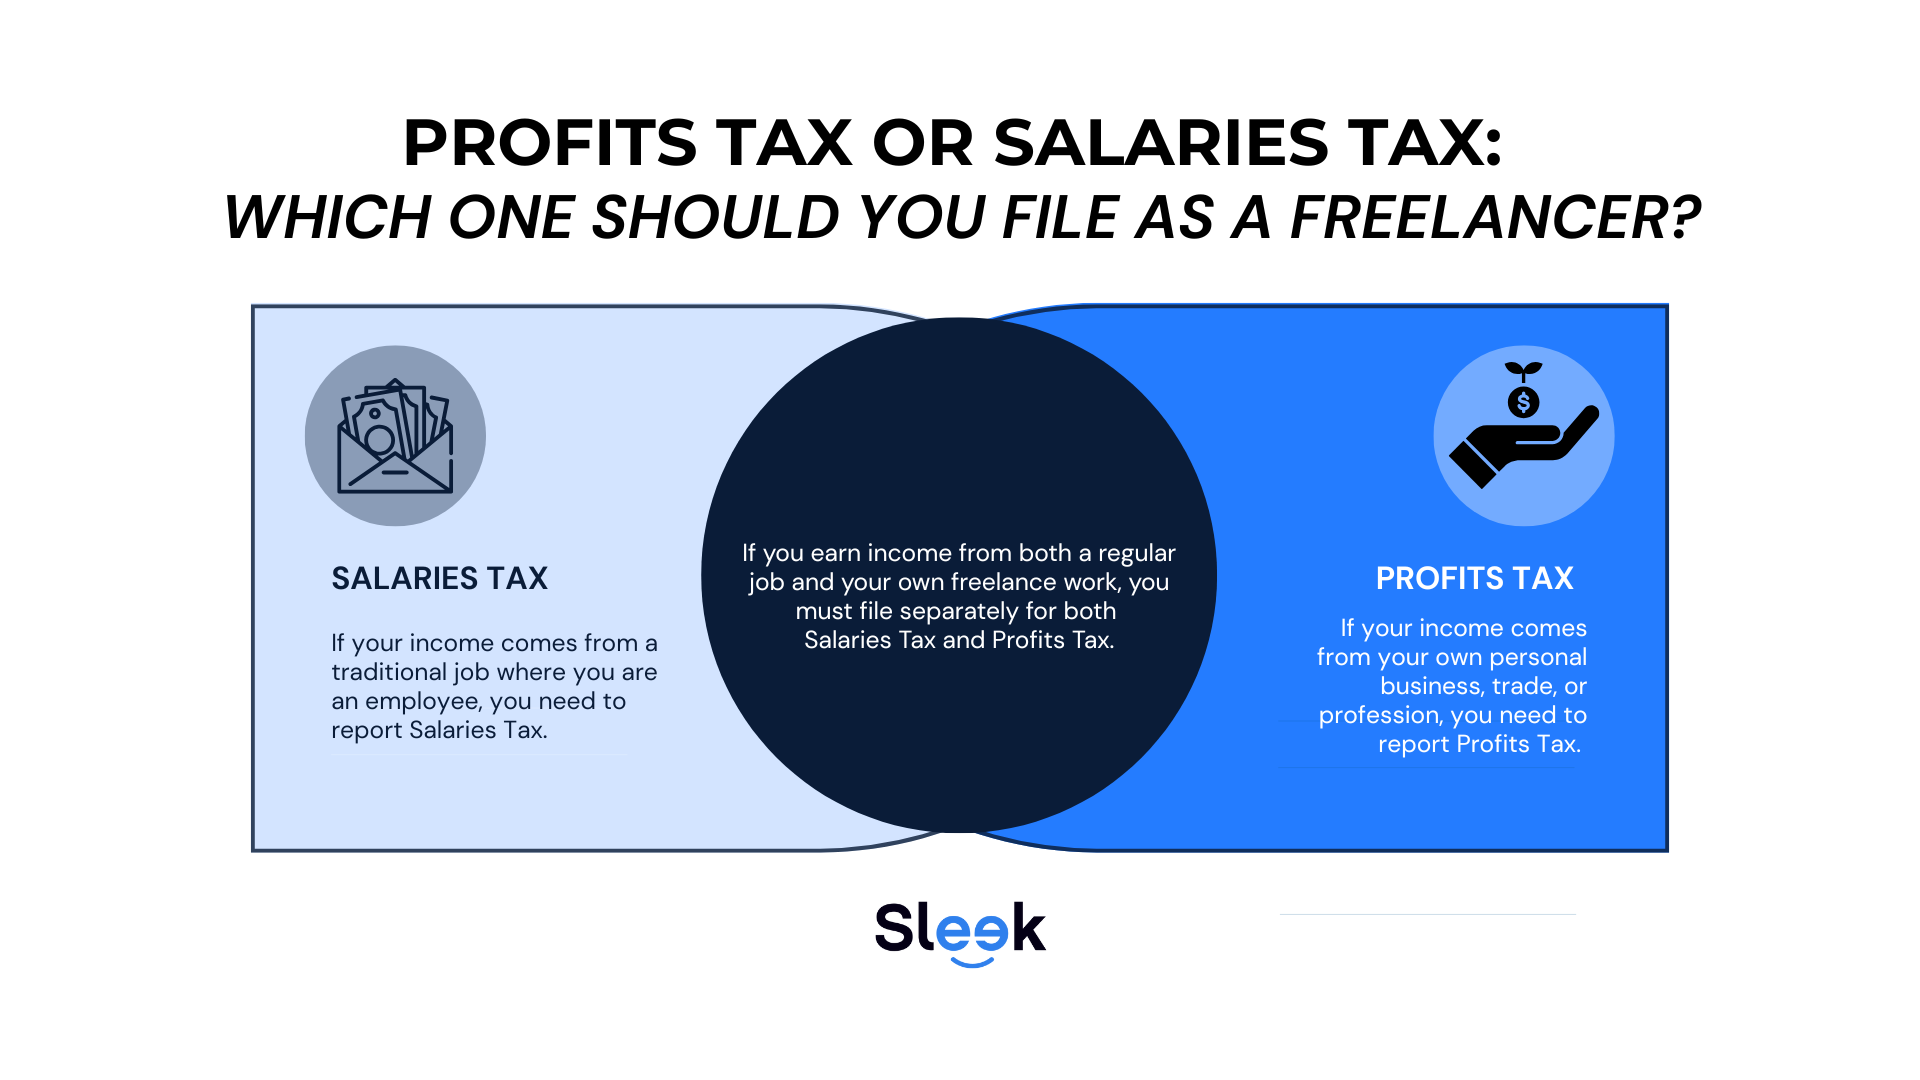
Hong Kong doesn’t have a separate “freelancer tax”. If you’re self-employed, your business profits are generally subject to Profits Tax.
The two-tiered rate for unincorporated businesses is 7.5% on the first HK$2 million of assessable profits and 15% above that. The 16.5% rate you may see is the corporation rate.
Business registration is due within one month of starting the business. Late registration can also create back-year fees.
Self-employed persons covered by MPF contribute 5% of relevant income, subject to the current minimum and maximum income levels.
Not sure whether your freelance income is profits tax or salaries tax?
Which tax? Profits tax on your business profits, reported in Part 5 of your individual tax return (BIR60). Not salaries tax.
What rate?7.5% on the first HK$2,000,000 of assessable profits, 15% above. Not the company 16.5%.
Do I register? Yes. Business registration is due within one month of starting.
Anything else?MPF at 5% of relevant income once you're above the minimum, paid by you as a self-employed person.
If you’re earning freelance income in Hong Kong, the first thing to know is that there’s no separate “freelancer tax”. If you’re genuinely self-employed, your business profits are generally taxed under Profits Tax, rather than a separate self-employment tax.
That answers the basic tax question, but there’s more to staying compliant. Business registration, MPF and filing requirements each have their own rules and deadlines, and they’re easy to overlook when you’re focused on the work itself.
In this guide, you’ll learn:
Whether your freelance income falls under Profits Tax or Salaries Tax
Which tax rates apply to you
How to calculate your taxable profits
What business registration and MPF require
When a limited company may make more sense
Do freelancers pay tax in Hong Kong?
Yes. If you’re genuinely self-employed, your freelance profits are generally subject to Profits Tax. Hong Kong doesn’t have a separate tax called “freelancer tax” or “self-employment tax”.
That distinction matters because freelance income can fall under Profits Tax rather than Salaries Tax, depending on the nature of the working arrangement. Once that’s clear, the main obligations are business registration, tax filing, MPF and record keeping.
What applies
When it applies
By when
Business registration
You’re carrying on a business in Hong Kong
Within 1 month of starting
Profits Tax
You have assessable business profits
By the date shown on your return
Notify the IRD
You’re chargeable but haven’t received a return
Within 4 months after the year of assessment ends, where applicable
MPF contributions
Your relevant income reaches the minimum level
Monthly or yearly
Record keeping
You’re carrying on a business
Keep records for 7 years
Is freelance income subject to Profits Tax or Salaries Tax?
Profits Tax, if you’re genuinely self-employed. The distinction matters because it affects how your income is taxed and which part of your tax return you complete.
The IRD looks at the overall working arrangement, not just what your contract calls you. The factors below are indicators, not a checklist, and no single factor decides the outcome.
Factor
More consistent with Profits Tax
More consistent with Salaries Tax
Who controls the work?
You decide how and when it’s done
The client controls it
Equipment and workspace
You provide them and bear the risk
The client provides them
Financial risk
You bear the risk of loss
The client bears the risk
Number of clients
Often several
Often one
How you’re paid
You invoice the client
You’re paid through payroll
The substance of the relationship matters more than the label. For example, if one client controls your hours, provides your equipment and pays you like an employee, the arrangement may be employment even if your contract calls you a freelancer.
If the status is unclear, it’s worth resolving before you file, because it determines whether the income belongs under Profits Tax or Salaries Tax.
Want the return, the deadlines and the MPF handled for you?
For an unincorporated business such as a sole proprietorship, the two-tiered Profits Tax rates are 7.5% on the first HK$2 million of assessable profits and 15% on the excess.
You may also see 8.25% and 16.5% online. Those are the corresponding corporation rates.
The key distinction is:
Entity
First HK$2 million
Above HK$2 million
Sole proprietor / other unincorporated business
7.5%
15%
Corporation
8.25%
16.5%
Unincorporated freelancers use 7.5% then 15%. The 8.25% and 16.5% bands are for companies only.
The two-tiered regime has additional rules where connected entities are involved, so the table is a general guide rather than a complete eligibility test.
How do you calculate your freelancer tax?
Business income − allowable expenses = assessable profits. Apply the profits tax rate to that. You’re taxed on profit, not on everything that reaches your bank account.
For an unincorporated business, profits tax has two tiers: 7.5% on the first HK$2 million of assessable profits, and 15% above that. A freelancer who invoiced HK$620,000 with HK$140,000 of allowable expenses stays in the first tier:
Business income
HK$620,000
Less allowable expenses
(HK$140,000)
Assessable profits
HK$480,000
Profits tax at 7.5%
HK$36,000
Two things can change that figure: which expenses you can deduct, and whether you elect personal assessment.
What expenses can self-employed people deduct in Hong Kong?
Expenses incurred in producing your business profits.
Usually deductible: software subscriptions, equipment hire, professional insurance, accounting fees, marketing and business travel.
Your MPF: your own mandatory contributions count as a business expense, according to the IRD. As a self-employed person, you can be required to contribute at most HK$18,000 a year.
Split mixed-use costs: for things like your phone or internet, claim only the business share.
Worked example: profits tax vs personal assessment
A single sole proprietor has HK$400,000 of assessable profits in 2025/26, with no other income or deductions. The profit figure is illustrative.
Step
Profits tax only
Personal assessment
Assessable profits
HK$400,000
HK$400,000
Less basic allowance
Not available
(HK$132,000)
Taxed on
HK$400,000
HK$268,000
Rate
7.5%
Progressive, 2% to 17%
Tax
HK$30,000
HK$27,560
Less 2025/26 tax reduction
(HK$3,000)
(HK$3,000)
Tax payable
HK$27,000
HK$24,560
Personal assessment working: 2%, 6%, 10% and 14% on successive HK$50,000 bands (HK$1,000 + HK$3,000 + HK$5,000 + HK$7,000), then 17% on the remaining HK$68,000 (HK$11,560), totalling HK$27,560. This is below the standard-rate cap of 15% on net income (HK$60,000), so the progressive figure applies. The 2025/26 reduction is 100% of the tax, capped at HK$3,000, and applied automatically.
Result: personal assessment saves HK$2,440 in this case.
Not always lower: a spouse’s income, other allowances or higher profits can change the answer, so work out both before you elect.
From 2026/27: the basic allowance rises to HK$145,000.
How can you legally reduce your tax as a freelancer?
There’s no separate self-employment tax in Hong Kong, so savings come from lowering your assessable profits and choosing how you’re assessed:
Claim every allowable expense: including the business share of mixed-use costs. See what you can deduct.
Count your MPF: your own mandatory contributions are an allowable business expense.
Write off computers and software: spending on computer hardware and software for the business can usually be deducted in full in the year you buy it.
Compare personal assessment: it can lower your bill, as in the worked example, but not always.
Carry losses forward: file a return in a loss year, and the loss can be set against future profits.
Look out for one-off reductions: for 2025/26, the IRD reduces profits tax and tax under personal assessment by 100%, up to HK$3,000, automatically.
Do you need business registration as a freelancer?
Yes, if you’re carrying on a business. The IRD requires sole proprietors and partnerships to apply for business registration within one month of the date the business starts. The clock runs from that date, not from when you decide to register.
No exemption for small or part-time work: earning a little, or freelancing alongside a job, doesn’t remove the requirement on its own.
Penalty: failing to register is an offence, with a maximum fine of HK$5,000 and one year’s imprisonment.
Cost: a one-year certificate is HK$2,350, including the levy.
Registering late costs more than the penalty. The IRD states that anyone applying more than 12 months after commencing business pays registration fees for the current year and all back years. A freelancer who quietly traded for three years owes three years of fees, not one. That is the point at which "I'll sort it later" stops being cheap.
What about MPF for self-employed freelancers?
You contribute for yourself, at 5% of relevant income. No employer is doing it for you, and this is the obligation freelancers discover latest.
In one line: a Hong Kong self-employed person pays 5% of relevant income between HK$7,100 and HK$30,000 a month, capped at HK$1,500 a month (HK$18,000 a year), with no contribution required below the minimum.
Minimum level: HK$7,100 a month, or HK$85,200 a year. Below that, no contribution is required
Maximum level: HK$30,000 a month, or HK$360,000 a year
Cap: contributions stop at HK$1,500 a month, or HK$18,000 a year
Frequency: monthly or yearly, on or before the contribution day
Tax relief: mandatory contributions are tax-deductible, up to HK$18,000 a year
There’s also a route most guides skip. A self-employed person with a business loss can declare it to the eMPF Platform and suspend contributions until income returns to the minimum level. That matters in a thin year, and it only helps if you tell them.
When do freelancers file and pay tax?
You report freelance profits in Part 5 of your individual tax return (BIR60), not in the employment-income section. Sole proprietors usually get longer to file than employees with employment income only.
The IRD issues individual tax returns around early May each year. From there:
Employees: generally about one month to file
Sole proprietors: generally about three months
Filing electronically: adds a further month either way
For the 2025/26 year of assessment, returns were issued on 4 May 2026, giving sole proprietors until 4 August 2026 to file on paper. Always work to the deadline printed on your own return, and see Hong Kong filing deadlines for the wider timetable.
No return in the post doesn’t mean nothing to file. If you’re chargeable to Profits Tax and the IRD hasn’t sent you a return, you have to notify them in writing yourself, no later than four months after the end of your basis period. If your accounting date is 31 March, that means 31 July.
Tip
Your first bill will look too big, and it usually isn't wrong. Hong Kong charges provisional tax: the assessment covers the year just assessed plus an advance toward the next one. A freelancer expecting tax on one year's profits can find close to two years' worth demanded at once. Budget for it in year one rather than discovering it in the demand note.
What mistakes do freelancers commonly make?
The most expensive mistakes are usually simple assumptions about which rules apply.
Using the 16.5% corporation rate
That isn’t the standard two-tiered rate for a sole proprietor. Unincorporated businesses use 7.5% and 15%; corporations use 8.25% and 16.5%.
Assuming part-time work doesn’t need registration
The registration rule applies to carrying on a business, not just full-time work. Side income can still amount to a business.
Waiting for a tax return to arrive
No return doesn’t necessarily mean no filing or notification obligation. If you’re chargeable and haven’t received a return, check whether you need to notify the IRD.
Forgetting MPF
Self-employed people are responsible for their own MPF contributions. There’s no employer deducting and paying them on your behalf.
Mixing personal and business spending
Keep enough records to show which costs relate to the business. For mixed-use expenses, the business portion may need to be identified rather than claiming the entire cost.
When does a limited company make more sense?
A limited company may be worth considering when your contracting, liability or administrative needs have outgrown a sole-proprietor setup. Incorporation also brings its own accounting, filing and audit obligations, so it shouldn’t be treated as an automatic tax-saving move.
Consider the change when:
Clients prefer or require a company as the contracting party.
You want the protection of a separate legal entity for larger projects.
You’re hiring or the business structure is becoming more complex.
You’re comparing company and sole-proprietor tax rates alongside the extra compliance.
Do I need business registration if freelancing is just side income?
Yes, if you’re carrying on a business. The one-month rule turns on whether there’s a business, not on whether it’s your main income or how much it earns. Occasional one-off work for a friend is a different case from regularly invoicing clients, and the second one is a business.
What if all my clients are overseas?
You may still be chargeable. Hong Kong taxes profits by where they arise, not by where your clients are, so an overseas client list does not by itself put your profits outside the charge. Where the work is performed matters more. If most of yours is done outside Hong Kong, get that assessed rather than assumed.
What happens in a year I make a loss?
You still file. A loss is carried forward against future profits, so reporting it protects a deduction you would otherwise lose. Separately, a self-employed person with a business loss can declare it to the eMPF Platform and suspend MPF contributions until income recovers.
Should I elect personal assessment?
Only if it lowers your tax, and that depends on your figures. Personal assessment lets your profits be assessed with your allowances applied. For 2025/26 the basic allowance is HK$132,000, which can help if profits are modest or you have losses elsewhere. It is not automatic and not always better. Run both before electing.
How do I actually register for MPF as a freelancer?
You enrol yourself in a scheme rather than being enrolled by an employer. You pick a trustee, join as a self-employed person, declare your relevant income, and then contribute monthly or yearly. Your income declaration is what sets the contribution, so keep it current when your earnings change.